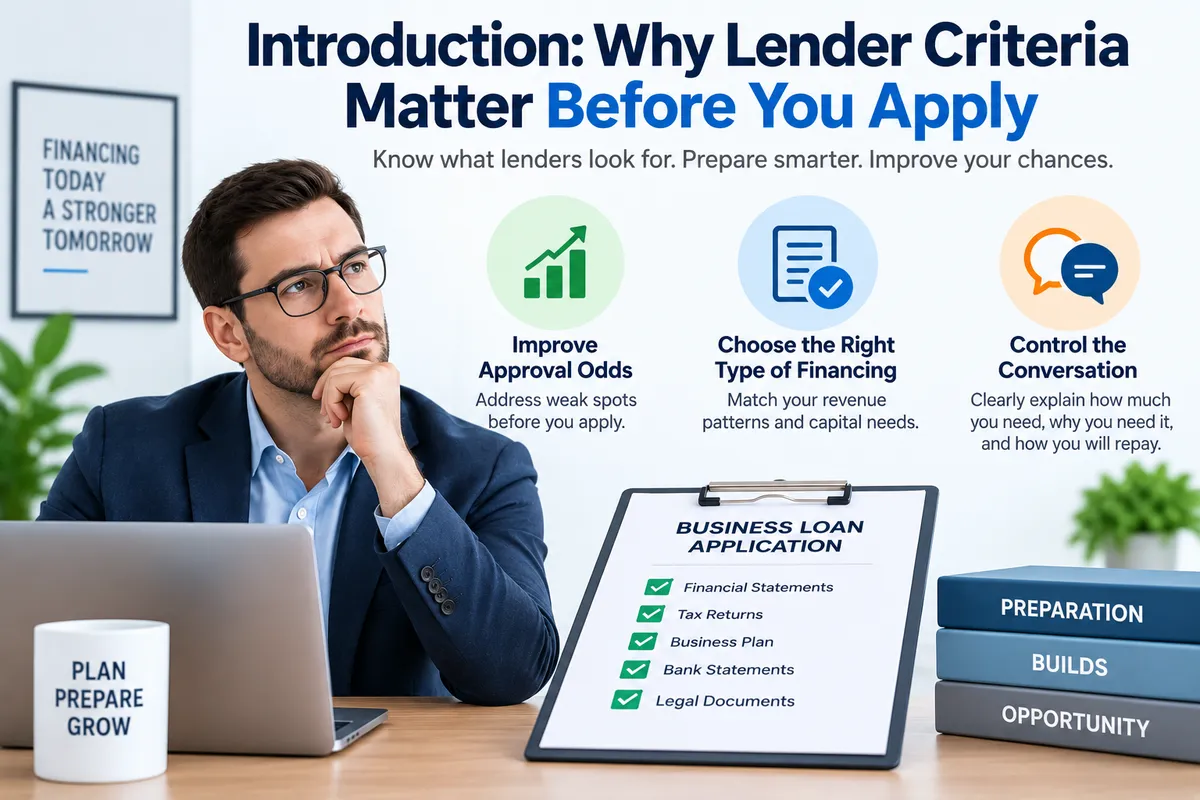
Introduction: Why Lender Criteria Matter Before You Apply
When you apply for a business loan, the lender is not guessing. An underwriter follows a structured credit policy that looks for specific readiness signals, such as consistent cash flow, responsible use of credit, and organized financial reporting.
If you understand those criteria in advance, you can:
●Improve approval odds by addressing weak spots before any application is submitted.
●Choose the right type of financing that aligns with your revenue patterns and capital needs.
●Control the conversation with clear explanations for how much you need, why you need it, and how you will repay.
Lenders reward preparation. Clean books, clear documentation, and a realistic repayment plan signal that you respect both your own numbers and the capital you are requesting.
Next step: Complete the brief Funding Status Check at this link to see how your business currently presents to lenders and where to focus before you apply: https://form.jotform.com/252325489732160
Key Criteria Lenders Evaluate in a Business Loan Application
Lenders review business loan requests through a few core filters, all tied to one question, how reliably will this be repaid. Underwriters look for clear, verifiable indicators in the following areas.
Creditworthiness
Personal and business credit reflect how you have handled obligations over time. Underwriters review scores, utilization, payment history, and derogatory items, then compare what they see to the amount and structure you are requesting.
Financial Strength and Cash Flow
Lenders study your income statement, balance sheet, and bank activity. They look for consistent revenue, positive trends, and cash flow that can support the new payment with a reasonable cushion. Unexplained swings in deposits or expenses trigger questions.
Loan Purpose and Business Plan
A clear, written use of funds, tied to a practical plan, signals management strength. Underwriters want to see how the capital supports revenue, margins, or stability, and how that translates into repayment.
Collateral and Industry Risk
Some structures require collateral, such as equipment or receivables, with documentation that supports the stated value. Lenders also review your industry profile, business model, and operating history to gauge stability and sensitivity to downturns.
Next step: Get a fast, lender aligned read on where you stand by completing the Funding Status Check: https://form.jotform.com/252325489732160
How to Prepare Your Business for Lending Approval
To prepare your business for approval, focus on what underwriters actually verify, clean credit profiles, consistent and documented cash flow, a specific use of funds, and supportable collateral. Your goal is a file that answers questions before the lender has to ask them.
Strengthen Personal and Business Credit
●Bring accounts current and keep on time payments consistent.
●Reduce revolving utilization where possible.
●Separate business and personal spending, and confirm your business credit profile is active and accurate.
Organize Financial Documents
●Prepare current financial statements and tax filings.
●Download clean bank statements with clear, business related activity.
●Reconcile your books so reported profit and bank activity align.
Clarify Loan Purpose and Plan
●Define a specific use of funds and target amount.
●Map how the financing supports revenue, margins, or stability.
●Outline a repayment plan tied to realistic cash flow.
Document Collateral, When Relevant
●List assets you can pledge with supporting documents.
●Confirm ownership, condition, and any existing liens.
Next step: Get a lender aligned readiness snapshot by completing the Funding Status Check: https://form.jotform.com/252325489732160
Common Pitfalls to Avoid When Applying for a Business Loan
Lenders decline a lot of applications for preventable reasons. Underwriters look for consistency, clarity, and capacity to repay, so anything that creates doubt in those areas works against you.
Documentation Gaps and Inconsistencies
●Missing or outdated financials such as partial tax returns or unreconciled statements.
●Bank activity that does not match reported revenue or profit with no clear explanation.
●Unorganized files that force the lender to chase items or guess.
Unclear Loan Purpose and Weak Repayment Logic
●No specific use of funds, only general working capital language.
●Loan amounts that do not match your budget or projected impact.
●Repayment plans that ignore seasonal or uneven cash flow.
Credit Issues You Do Not Address
●Recent late payments or high utilization with no written context.
●Disputes or derogatory items that you have not cleaned up or explained.
Underwriters notice silence. If you know there are issues, address them directly in writing and back up your explanation with documents.
Next step: Use the Funding Status Check to surface these pitfalls before a lender does and prioritize what to fix next: https://form.jotform.com/252325489732160
FAQs: Avoiding Common Business Loan Application Mistakes
●What is the fastest way to reduce application red flags? Clean up late payments, reconcile your books, and be specific about use of funds and repayment.
●Will one late payment automatically trigger a decline? Not always, but underwriters expect a clear explanation and evidence that the issue is resolved.
●Can I apply if my financials are not fully updated? You can, but incomplete financials usually slow review and increase the chance of a decline.
●How detailed should my loan purpose be? Break it into line items with estimated amounts and timing tied to your operations.
●What if my cash flow is seasonal? Flag that early, show a full year of bank activity, and structure your repayment logic around those cycles.
●Do lenders care about small inconsistencies? Yes, even small gaps can raise questions about accuracy and management control.
●How can I see issues before I apply? Complete the Funding Status Check and review your credit, cash flow, and documentation through an underwriting lens.
Conclusion: Taking Control of Your Business Financing Journey
Lenders are not looking for perfection, they are looking for reliable repayment, clean documentation, and a clear story that makes sense. When you understand how underwriters think, you stop guessing and start presenting your business in a way that matches their review process.
Prepared owners get better outcomes. That means:
●Credit profiles that show responsible behavior, with known issues addressed in writing.
●Financials that tie together, from tax returns to bank activity to internal reports.
●A loan request that is specific, documented, and realistic for your cash flow.
●Collateral and guarantees that are supported with clear, current records when relevant.
You cannot control every approval decision, but you can control how ready your file is and which types of financing you pursue.
Next step: Get a clear, underwriting aligned view of where you stand by completing the Funding Status Check: https://form.jotform.com/252325489732160
FAQs: Taking Control of Your Business Financing Path
●How do I know if my business is truly loan ready? Review credit, cash flow, and documentation using lender style criteria, or use a structured readiness checkup.
●What should I fix first if my profile has several issues? Start with on time payments and reconciled financials, then address documentation gaps and unclear loan purpose.
●Can preparation really improve my terms, not just approval odds? Strong files tend to qualify for a broader range of offers, which can support better structures and pricing.
●How often should I review my lending readiness? Build a recurring review into your financial routine so you are not starting from zero when an opportunity or need appears.
●What if I was declined before? Treat the decline as an underwriting memo, identify the specific reasons, then rebuild your profile and documentation around those points.
●How can I assess my current position without applying? Complete the Funding Status Check and evaluate your credit, cash flow, and paperwork against standard lender expectations.